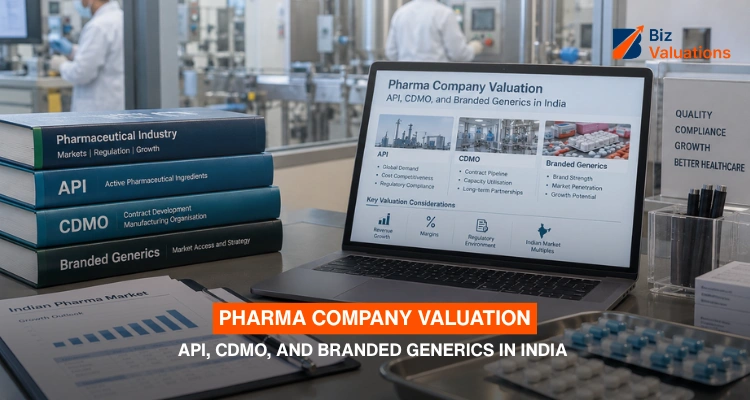
Pharma Company Valuation: API, CDMO, and Branded Generics in India
 Saurobh Barick
on
Introduction
India runs one of the most diverse pharma industries in the world. That diversity creates a real valuation problem. An Active Pharmaceutical Ingredient (API) maker should never get the same treatment as a Contract Development and Manufacturing Organisation (CDMO). A CDMO that serves global innovators is a different animal from a domestic branded-generics firm. A branded-generics firm with a strong chronic-therapy franchise deserves its own multiple too.
Too many pharma valuations still lean on one lazy line. They say Indian pharma firms trade at X times EBITDA. That line is dangerously simple. Pharma company valuation in India depends on the real cash engine behind the business. It does not depend on one industry-wide number.
An API maker's value hinges on chemistry complexity, regulatory approvals, customer concentration, product mix, plant use, environmental compliance, China dependency, and export exposure. A CDMO's value shifts toward the molecule pipeline, customer relationships, development-stage contracts, project visibility, technical depth, regulatory track record, and switching costs. A branded-generics firm's value tracks brand equity, physician reach, therapy mix, sales-force productivity, prescription generation, and the split between chronic and acute drugs.
These three models are fundamentally different. A credible pharmaceutical company valuation in India needs more than a sector-average multiple. It needs a clear read on what creates durable cash flow. This guide explains how API, CDMO, CRDMO, and branded-generics firms get valued in India. It covers the methods that matter most. It covers what investors often miss. It explains why specialist pharma valuation experience changes the final number. Biz Valuations is an IBBI Registered Valuer and SEBI Category I Merchant Banker firm. We have delivered 3,500+ certified valuations across 35+ industries, including deep work in pharma and healthcare manufacturing.
Key Takeaways
- One multiple never fits all pharma models. API, CDMO/CRDMO, and branded generics carry different risk profiles. This holds true even at identical EBITDA levels.
- Business model classification comes first. Before you pick a multiple, identify whether the firm earns from chemistry, contract services, or a branded prescription franchise.
- Read customer concentration in context. A high revenue share from one buyer is not always risky. It depends on how deep and long that relationship runs.
- CDMO and CRDMO firms need forward-looking analysis. Trailing EBITDA alone understates the value in development-stage projects.
- Working capital and compliance capex quietly eat value. Schedule M upgrades and receivables can shrink a healthy EBITDA into a much smaller free cash flow number.
- Regulatory and environmental risk can destroy value fast. Warning letters and effluent liabilities deserve as much scrutiny as the income statement.
- Sum-of-the-parts valuation matters for mixed businesses. One blended multiple across API, CDMO, and formulation revenue can misstate value by hundreds of crores.
- Specialist, sector-specific expertise pays off. A firm that separates API, CDMO, and branded-generics economics gives a more defensible, investor-ready number.
Why Pharma Company Valuation in India Demands Specialist Analysis
India's pharma industry blends manufacturing scale with scientific talent. It blends process chemistry with branded formulations. It exports generics globally. It also builds sophisticated contract-development skills. On top of this, it sits under intense regulatory watch.
A pharma firm can look profitable today. It can still face fast value loss tomorrow. A plant may fail an inspection, or an export facility may get a warning letter. A key API may lose pricing power, or a large customer may shift sourcing elsewhere. A product may fall under price control. Compliance capex may spike, a molecule may face new competition, working capital may expand, or customer concentration may turn excessive.
The reverse also holds true. An ordinary-looking manufacturer can build real value through hard-to-copy chemistry, regulatory approvals, long client relationships, technical know-how, complex products, high switching costs, and validated processes. The balance sheet rarely captures any of this. That is why pharma business valuation needs rigorous financial analysis. It also needs real commercial understanding of the model underneath the numbers.
India's Pharma Sector Is Shifting from Volume to Capability
For decades, people called India the "pharmacy of the world." That label still holds some truth, but it no longer tells the full story. Indian manufacturers are moving toward higher-complexity work. This includes speciality APIs, peptides, and high-potency APIs. It includes complex generics, biosimilars, injectables, oncology products, sterile manufacturing, CRDMO services, and drug-development support.
This shift matters directly for valuation. A firm earning 18% EBITDA margins from plain generic APIs should not get the same multiple as a strong CDMO. A CDMO with recurring global customers, long molecule lifecycles, and high switching costs deserves more. Margin alone tells you very little. Two firms can both post 25% EBITDA margins while carrying completely different risk profiles. Accurate pharmaceutical company valuation India work starts with precise classification, not the margin line.
The First Step: Identify the Pharma Business Model
Before picking any multiple, ask a simple question first: what business is actually being valued here? An Indian pharma firm may sit in one or more segments. These include API manufacturing, CDMO, CRDMO, and branded generics. They also include generic formulations, specialty pharma, biologics, biosimilars, and pure contract manufacturing. Each segment carries its own risk profile, capital intensity, and customer economics. Treating them as interchangeable produces unreliable numbers, and it is the single most common mistake in pharma valuation methods used by generalist advisors.
API Company Valuation in India
API manufacturing has long been one of India's core strengths. On the surface, the model looks simple. Raw materials go in. Chemical processes turn them into active ingredients. Formulation manufacturers then buy the output. But valuation differences inside this one segment can be enormous.
A commodity API producer competes mainly on price. That is a fundamentally different business from one making difficult chemistry. Difficult chemistry includes controlled substances and high-potency APIs. It includes oncology APIs, peptides, and sterile APIs. It includes niche intermediates and complex multi-step synthesis. The harder the chemistry, the stronger the barrier to entry.
Here are the key drivers in API company valuation:
- Product complexity. Commodity products draw lower multiples since customers can switch suppliers easily. Complex molecules need difficult synthesis, hazardous chemistry, specialised equipment, and regulatory validation, all of which support stronger margins and higher entry barriers.
- Customer concentration. Say a firm earns 42% of revenue from one customer, 24% from a second, and 10% from a third. That looks profitable on paper, but 66% of revenue rests on just two relationships. Losing one customer could hurt plant use and EBITDA hard, so a fair valuation may use a lower multiple or a higher discount rate.
- Regulatory approvals. A plant serving regulated export markets may hold USFDA registrations, EDQM approvals, WHO GMP status, CEPs, DMFs, and a clean audit history. Approvals alone do not create value, but they raise entry barriers. A plant with a long clean record can deserve a premium.
- Raw-material dependency. API economics are sensitive to key starting materials. Heavy reliance on one foreign source, especially China, raises risk. The valuation should check supplier concentration, import dependency, backward integration, and input-price swings.
- Capacity use. A plant running at 85% use behaves very differently from one at 45%. High use is not automatically better either. A firm near full capacity may need heavy capex to keep growing.
Worked example: An Indian speciality API manufacturer reports revenue of ₹300 crore. Its EBITDA is ₹54 crore, an 18% margin. Its net debt is ₹60 crore. Customer concentration is moderate. Export exposure is strong. Several molecules are hard to manufacture. Comparable companies support an EV/EBITDA range of 9x to 12x. Picking 10.5x gives an enterprise value of ₹567 crore. Subtracting net debt puts equity value at ₹507 crore.
That number should never get accepted mechanically. The analyst must still weigh pipeline strength and regulatory track record. Plant use and customer concentration matter too. So do capex needs, environmental liabilities, and working-capital intensity. The multiple is the end of the analysis. It is never the starting point.
CDMO Valuation in India
The CDMO sector is one of the most closely watched corners of Indian pharma right now. CDMOs do the work pharma and biotech firms prefer not to build in-house. At the basic level, a CDMO manufactures to customer specifications. At the higher end, a CRDMO adds much more. It adds discovery chemistry and route development. It adds process development and analytical development. It adds clinical-stage manufacturing and regulatory support. This deepens the customer relationship considerably.
The best CDMO businesses are not just selling kilograms of product. They are selling scientific capability and regulatory confidence. They are selling development expertise and manufacturing reliability. Confidentiality and speed to market matter too. These traits justify meaningfully different CDMO valuation multiples from plain manufacturing.
High switching costs sit at the centre of this story. Changing a pharma manufacturer is nothing like switching an office-supply vendor. A customer may need to validate a new facility, run audits, transfer processes, reproduce stability data, and secure fresh approvals. Once a CDMO gets embedded in a commercial molecule, the relationship can run for years and generate recurring revenue.
Molecule lifecycle adds real optionality too. A CDMO may start with a customer at the preclinical stage, when revenue is small. If the molecule clears Phase I, II, and III, then wins approval and launch, the CDMO's revenue can expand many times over. Valuation should study the pipeline, not just today's revenue line.
Consider a CDMO with 25 active customer projects. Eight sit in preclinical stage. Six sit in Phase I. Five sit in Phase II. Three sit in Phase III. Three are already commercial. A simple revenue multiple ignores the value inside that pipeline. But assuming every project reaches commercial success is equally unrealistic. A better approach uses probability-adjusted forecasts and scenario analysis. It uses expected commercialisation rates and historical conversion data. Probability-weighting revenue by development stage matters most in CRDMO work.
Customer concentration needs careful reading here too. A CDMO earning 35% of revenue from one global customer looks concentrated. But say that customer runs 15 active molecules, has a ten-year relationship, holds multiple commercial products, and keeps investing in development. The real concentration risk may be lower than the raw number suggests. Compare that with a firm earning the same 35% from one annual tender. Same percentage, completely different economics.
Worked example: A mid-sized Indian CDMO reports revenue of ₹500 crore, EBITDA of ₹125 crore (a 25% margin), and net debt of ₹80 crore. Regulated-market revenue is 65%, commercial molecules number 12, and development-stage projects total 28. The top customer contributes 18% of revenue. Market evidence supports an EV/EBITDA range of 15x to 20x, depending on growth, capability, and pipeline visibility. Picking 17x gives an enterprise value of ₹2,125 crore. Subtracting net debt puts equity value at ₹2,045 crore.
The higher multiple versus a typical API firm reflects several things. It reflects stronger recurring relationships and better margins. It reflects a meaningful pipeline, regulatory capability, and sharper revenue visibility. The exact multiple still needs real market evidence behind it, not assumption.
CRDMO Valuation Requires Forward-Looking Analysis
CRDMO firms are especially hard to value on trailing EBITDA alone. A firm may spend heavily today on scientists, laboratories, pilot facilities, analytical capability, and speciality chemistry, so current EBITDA can understate future earnings. At the same time, projecting aggressive commercialisation can overstate value just as easily.
A discounted-cash-flow model earns its place here. It works best when growth visibility is strong, contracted programmes exist, capacity is expanding, and customer pipelines are documented. The market approach still plays a role, but forward EBITDA can matter more than historical EBITDA in a CRDMO context.
Branded Generics Valuation in India
Branded generics run on completely different economics. Here, the main asset is often not the plant. It is the brand. A branded-generics firm builds value through physician prescription behaviour. Therapy positioning and sales-force productivity matter here. So do brand recall, distribution reach, and doctor coverage. Manufacturing can often be outsourced entirely. The commercial franchise still commands a meaningful branded generics valuation on its own.
Therapy mix is critical here. Acute therapies, like short infections, behave very differently from chronic ones. Chronic therapies include diabetes, cardiology, hypertension, and neurology. Chronic brands typically show stronger recurring prescription behaviour. A patient on a diabetes medicine may stay on treatment for years. That creates far more predictable revenue than a short-course acute product. Two firms with identical revenue can deserve very different multiples. One may have a strong chronic franchise. The other may lean on commoditised acute products.
Brand concentration deserves the same nuance as customer concentration elsewhere. Say a firm generates ₹250 crore in annual sales. Its top five brands contribute 61% of revenue. That is not automatically risky. Say the leading brand has a fifteen-year track record. Say it has strong doctor loyalty and stable prescription growth. It can be a genuinely valuable asset. But say the same brand faces imminent generic substitution or price control. Then the concentration becomes a real concern.
Sales-force economics affect value directly too. The valuer should study the number of medical representatives, revenue per representative, doctor coverage, prescription conversion, attrition rates, and incentive costs. A firm reporting ₹300 crore in revenue could still run an inefficient sales force. That force may eat an outsized share of gross profit. A similarly sized peer with sharper prescription productivity earns stronger economics instead.
Pricing and National Pharmaceutical Pricing Authority (NPPA) exposure matter too. Products under price control lose pricing flexibility. The analyst needs to know which products face controls, the history of price increases, and margin compression risk. A forecast assuming flat 8% price increases across the whole portfolio is unrealistic if many products face pricing restrictions.
Worked example: An Indian branded-formulations firm reports revenue of ₹400 crore. Its EBITDA is ₹80 crore, a 20% margin. Its net debt is ₹20 crore. Chronic therapies make up 65% of sales. The top brand represents 12% of revenue. The top ten brands contribute 48%. Comparable evidence supports an EV/EBITDA range of 14x to 18x. Picking 16x gives an enterprise value of ₹1,280 crore. After net debt, equity value comes to ₹1,260 crore. A premium within that range can reflect strong chronic exposure and high prescription growth. It can also reflect diversified brands and a productive field force.
API vs CDMO vs Branded Generics: How the Valuation Approach Differs
The table below sums up how these three models diverge. It covers the factors that matter most in a pharma company valuation in India. Use it as a quick reference, not a substitute for full segment-specific analysis.
| Valuation Factor | API Manufacturing | CDMO / CRDMO | Branded Generics |
|---|---|---|---|
| Core value driver | Chemistry complexity and regulatory approvals | Customer relationships and pipeline depth | Brand equity and prescription behaviour |
| Typical India EV/EBITDA range* | Roughly 7x to 12x | Roughly 14x to 20x | Roughly 13x to 18x |
| Revenue predictability | Moderate, tied to customer contracts | High for commercial molecules, variable for pipeline stage | High for chronic therapy franchises |
| Concentration lens | Share of revenue from top customers | Relationship depth, not raw percentage | Brand history and prescriber loyalty |
| Capital intensity | High (plant, utilities, environmental systems) | High (labs, pilot plants, compliance) | Moderate (field force, marketing, distribution) |
| Preferred valuation method | Market approach, DCF for expansion-stage plants | DCF with probability-weighted pipeline | Market approach, income approach for chronic brands |
| Biggest single risk | Regulatory action, customer loss, import dependency | Molecule attrition, customer concentration | Price control, generic erosion, brand fatigue |
Ranges above are illustrative. They rest on general market evidence. Actual multiples depend on firm-specific growth, quality, and deal context. Always confirm with a full business valuation engagement.
Why One Pharma Multiple Does Not Work
Take three companies. Each earns exactly ₹100 crore of EBITDA. They can still produce very different enterprise values. A commodity API business might support an 8x multiple. That gives ₹800 crore. A high-quality CDMO might support an 18x multiple. That gives ₹1,800 crore. A branded chronic-pharma firm might support a 15x multiple. That gives ₹1,500 crore. Same EBITDA. Three very different outcomes.
The gap reflects predictability and competitive barriers. It reflects intellectual property and customer relationships. Regulatory risk and growth prospects play a role too. So do capital intensity, franchise strength, and switching costs. This single principle sits at the heart of every credible pharma company valuation India engagement.
The Three Main Valuation Approaches
A professional pharma valuation normally weighs three approaches. The Income Approach values future economic benefits. Discounted cash flow works well when growth, capex, or margins are set to shift. The Market Approach compares the firm against listed peers and recent deals. It uses metrics like EV/Revenue, EV/EBITDA, P/E, and EV/EBIT. It sometimes uses molecule-specific or product-specific measures too. The Asset Approach applies mainly in narrow cases. These include asset-heavy firms, weak earnings, or genuine liquidation scenarios.
Most operating pharma businesses are not valued purely on asset value. A modern compliant facility can carry real economic value well beyond its book cost. Our Business Appraisal Services page covers how we blend these three approaches for manufacturing-heavy firms.
Discounted Cash Flow Valuation for Pharma Companies
DCF analysis earns its keep during transformation. A robust forecast should model product-level revenue and volume growth. It should model pricing, gross margins, and employee costs. R&D and selling expenditure matter here too. So do capex, working capital, and tax. CDMO firms often need project-level probability weighting on top. API companies need the forecast to reflect new products and qualification timelines. Branded-generics forecasts should address prescription growth and new launches.
Our DCF Valuation Services page walks through how we build these assumptions for pharma clients.
Risk-Adjusted NPV (rNPV) and Pipeline-Heavy Valuations
CRDMO firms and pipeline-heavy branded players need one more tool. A plain DCF can miss an important nuance: not every project reaches the market. Risk-Adjusted Net Present Value, or rNPV, fixes this gap. It applies stage-specific success rates to each project's cash flows. Then it discounts those adjusted flows back to today.
A preclinical project, a Phase II asset, and a molecule already in commercial supply carry very different odds. They should never get valued as if the odds were equal. rNPV matters most for CRDMO firms with several development-stage projects and for branded-pharma firms betting on unlaunched products. It matters far less for a stable API plant with no real pipeline. Industry data on phase-wise success rates offers a useful starting point, though every assumption should still get tailored to the specific therapy area.
Patent Cliff, Exclusivity, and Product Lifecycle Risk
Every branded or patent-linked product has a natural lifecycle. Revenue can fall sharply once patent protection or exclusivity ends and generic or biosimilar competition enters. For small-molecule branded products, the drop can happen almost overnight. Biologics and biosimilars tend to decline more slowly, since the biosimilar approval pathway remains more complex than the small-molecule generic pathway, including in India.
For branded generics valuation, this matters a great deal. Any firm with meaningful patent-linked revenue needs a clear view here. Which products face near-term exclusivity loss? Which competitors stand ready to enter? How fast do price and volume erode after entry? Ignoring this lifecycle risk is one of the fastest ways to overstate a forecast, especially when a handful of brands carry most of the revenue.
Working Capital Is Frequently Underestimated
Indian pharma companies can be working-capital intensive. Receivables often expand because of export customers, institutional contracts, channel inventory, and distributor terms. Inventory itself can be substantial too, given safety stock, raw materials, and validation batches. EBITDA is not cash flow. A firm generating ₹100 crore of EBITDA may still need ₹40 crore of fresh working capital every year. That firm looks very different from one that converts most EBITDA into free cash. This distinction should shape the final valuation conclusion, not sit buried in a footnote.
Capex and Schedule M Compliance
Regulatory compliance is becoming a bigger line item every year. India's revised Schedule M rules raised the bar sharply on Good Manufacturing Practices, premises, plant, equipment, documentation, quality systems, and manufacturing controls. For valuation, the practical question is simple: how much capital must the firm spend just to stay compliant and competitive?
Suppose a facility needs ₹30 crore for HVAC upgrades. It needs ₹15 crore for quality systems, ₹10 crore for laboratories, and ₹20 crore for equipment. That totals ₹75 crore. If the valuation model ignores this spend, enterprise value gets overstated. Compliance capex is an economic requirement, never just an accounting footnote.
Regulatory Risk Can Destroy Value Quickly
Pharma businesses can lose value faster than firms in most other sectors. Warning letters, import alerts, manufacturing suspensions, and data-integrity findings can hit hard. Product recalls, regulatory bans, and licence loss can follow. A valuer should study regulatory history with real care. A firm with a spotless record can justify lower risk assumptions. One with unresolved remediation issues needs different treatment. It may need higher discount rates, lower multiples, or explicit remediation capex in the model.
Environmental Compliance Matters for API Manufacturers
Chemical manufacturing creates real environmental exposure: effluent treatment, solvent recovery, hazardous waste, emissions, contamination risk, water usage, and remediation obligations. A plant can report an impressive EBITDA and still carry heavy environmental liabilities. An acquisition-focused API company valuation should never ignore these risks, since remediation costs can run into crores and directly reduce free cash flow.
Intellectual Property and Intangible Assets
Pharma companies often hold valuable assets that never fully show up on the balance sheet: product brands, patents, trademarks, dossiers, Drug Master Files (DMFs), customer relationships, technology, process know-how, and thehttps://bizvaluations.in/intangible-asset-valuation-india/ assembled workforce. Depending on the valuation's purpose, these assets may need separate measurement, most notably for acquisitions, purchase price allocation, and litigation. Our Intangible Asset Valuation guide covers how brands, DMFs, and know-how get valued as standalone assets.
Sum-of-the-Parts Valuation for Diversified Pharma Companies
Many Indian pharma companies run across multiple segments at once. Suppose API contributes ₹40 crore of EBITDA, CDMO contributes ₹50 crore, and branded generics contribute ₹60 crore. Applying one 12x multiple to the combined ₹150 crore implies an enterprise value of ₹1,800 crore.
A sum-of-the-parts (SOTP) valuation tells a different story. API at 9x equals ₹360 crore. CDMO at 18x equals ₹900 crore. Branded generics at 15x equals ₹900 crore. That totals ₹2,160 crore. The ₹360 crore gap shows why segment-level analysis matters. A blended average multiple can quietly misstate value either way.
Understanding enterprise value versus equity value matters here too. Our guide on Enterprise Value vs Equity Value breaks this down with Indian examples relevant to multi-segment pharma firms.
How Indian Pharma Valuation Multiples Compare with Global Benchmarks
Global M&A research on small and mid-size pharma companies offers a useful reference point, though Indian multiples usually sit lower due to company size, market depth, and currency factors. Recent global deal data shows a useful pattern. Generic manufacturers with EBITDA between roughly USD 10 million and USD 50 million trade around 12x EBITDA. That figure rises toward the mid-teens at larger scale. Production and distribution businesses in the same size bands command somewhat higher multiples, often mid-teens to high-teens.
These global figures are directional only, not a substitute for India-specific comparable analysis. They still offer useful context for benchmarking. This helps most when comparing an Indian CDMO or API business against global peers, especially with a strategic or cross-border buyer at the table.
Strategic Exit and M&A Premium Considerations
Small and mid-sized pharma firms often carry value tied to acquisition odds. Investors and promoters sometimes picture what a strategic buyer might pay, whether a larger domestic pharma group, a global generics company, or a private equity roll-up.
This should never work as a primary valuation method. It works better as a sanity check on a DCF or market-approach number. This holds especially for CDMO and speciality API firms, where global buyers have been actively acquiring capacity across India. A valuation built solely around an assumed exit premium stays speculative and hard to defend to auditors, regulators, or courts.
What Buyers Commonly Miss in Pharma Acquisitions
Buyers often anchor on headline EBITDA alone. They overlook compliance capex, working-capital intensity, and product or customer concentration risk. Regulatory observations, plant use, environmental liabilities, pricing erosion, molecule lifecycle, and owner dependence often go unchecked. The result can be overpayment. A well-prepared valuation should surface these issues before the deal closes, not after.
What Sellers Commonly Overlook
Sellers tend to make the opposite mistake. They focus purely on historical earnings and miss the hidden strategic value underneath. A CDMO may hold late-stage molecules, sticky global customers, and under-utilised capacity. A branded-generics firm may hold valuable prescription franchises that never show up on the balance sheet. An API maker may hold difficult chemistry capability that a rival would need years to recreate. A proper valuation should capture every one of these strengths, not just the numbers on the P&L.
Why Specialist Valuation Experience Matters
Industry knowledge matters as much as spreadsheet skill here. A firm that applies one broad industry multiple rarely produces a defensible number. The better approach evaluates API separately from CDMO, and CDMO separately from branded generics. It examines product and customer concentration, EBITDA normalisation, regulatory status, capacity use, growth pipeline, working capital, compliance capex, and recent transactions.
A credible valuation firm should defend its full methodology. This means the comparable companies chosen and the EBITDA normalisation applied. It means the projections used, the discount rate selected, and any regulatory adjustments. That discipline separates specialist pharma valuation from a generic business appraisal.
Information Typically Required for a Pharma Company Valuation
A professional engagement commonly needs three to five years of audited statements, the latest management accounts, and a business plan. Product-wise, customer-wise, and geography-wise revenue data all matter, along with manufacturing capacity, use data, and regulatory approvals. Plant details, product registrations, customer contracts, pipeline information, R&D spending, capex plans, a debt schedule, and working-capital detail round out the list. CDMO firms usually need project-level pipeline detail, while branded-generics companies need brand-level sales data.
Our Business Valuation Services page outlines the standard documentation checklist we request across sectors, including pharma.
Final Thoughts: Pharma Valuation Is About Quality of Earnings, Not Just EBITDA
The most important lesson here is simple. Pharma revenue is not homogeneous. ₹100 crore from commodity APIs does not carry the same risk as ₹100 crore from a diversified CDMO portfolio. ₹100 crore from a mature chronic franchise deserves different treatment from ₹100 crore earned through low-margin tenders.
The valuation professional must look beneath the financial statements. For API businesses, ask how difficult the chemistry is, how concentrated the customers are, and how much regulatory capex lies ahead. For CDMO and CRDMO businesses, ask about customer stickiness and pipeline depth, and how many molecules can realistically reach commercial manufacturing. For branded generics, focus on brand strength, the therapies driving growth, field-force productivity, and pricing sustainability.
These questions explain why pharma valuation demands specialist judgment. A strong valuation reconciles financial performance with commercial position, regulatory quality, growth prospects, and market evidence. The final multiple should reflect that full analysis. It should never replace it.
This sector-specific approach helps every type of stakeholder. It helps investors weighing acquisitions and promoters preparing to raise funds. It helps family offices reviewing ownership value and private-equity funds assessing entry or exit. This matters especially in India today, as the pharma industry keeps moving away from low-cost manufacturing toward higher-value APIs, complex generics, and CRDMO services.
The firms that build the most durable value combine scientific capability, regulatory credibility, customer trust, manufacturing reliability, and disciplined capital allocation. The best pharma valuations recognise exactly where that value comes from.
Top 10 Frequently Asked Questions About Pharma Company Valuation in India
About Biz Valuations
Biz Valuations provides independent business, equity, and intangible-asset valuation services across India for transaction, tax, financial-reporting, strategic, litigation, and investment purposes. Our capabilities span pharmaceutical company valuation, API manufacturer valuation, CDMO and CRDMO valuation, branded-generics valuation, purchase price allocation, intangible-asset valuation, financial modelling, and shareholder valuation.
Our pharma valuation methodology goes beyond an industry-average multiple. The analysis focuses on the real drivers of value. These include manufacturing economics, product-therapy mix, customer concentration, and regulatory profile. Capacity use, working capital, R&D pipeline, brand strength, and comparable transactions matter too.
We have delivered 3,500+ certified valuations across 35+ industries, with 15+ years of expertise and $40+ billion in total valuation value delivered. Our team holds IBBI Registered Valuer and SEBI Category I Merchant Banker credentials. This lets us certify valuations across the Companies Act, FEMA/FDI, Income Tax, SEBI, and Ind-AS/IFRS frameworks, all under one roof.
Whether you are valuing an API manufacturer, CDMO, CRDMO, or branded-generics company, start with the same principle. Understand the economics of the individual business first. Never apply a generic pharmaceutical multiple by default. Biz Valuations works with promoters, investors, corporate groups, and advisers. We prepare independent pharma valuations backed by real financial analysis and market evidence.
Mr. Saurobh Barick
Registered Valuer (IBBI) & Valuation Expert
DCF & Fair Market Value Valuations | FEMA, Income Tax & Companies Act | 409A Valuation | M&A, Fundraising valuation | Cross-Border & Startup/Business Valuation | SME IPO AdvisorySaurobh Barick is a Registered Valuer with the Insolvency and Bankruptcy Board of India (IBBI) and a finance professional with over 15 years of experience in valuation and financial advisory services.